The DSO Number Someone Used as a Coaster
THE SHORT ANSWER
Days sales outstanding is the average number of days between sending an invoice and collecting payment, calculated as accounts receivable divided by annual revenue, multiplied by 365. At 30 days, revenue converts to cash quickly. At 75 days, you are financing your entire customer base for two and a half months.
A CFO in Paul Whitley's book spends fourteen months trying to get her CEO to look at one number.
She includes it in four monthly reports. She adds a footnote to two board presentations. She sends a direct email with the subject line "Q3 Receivables - Action Required." He reads the first sentence, notes it for follow-up, and attends three client lunches.
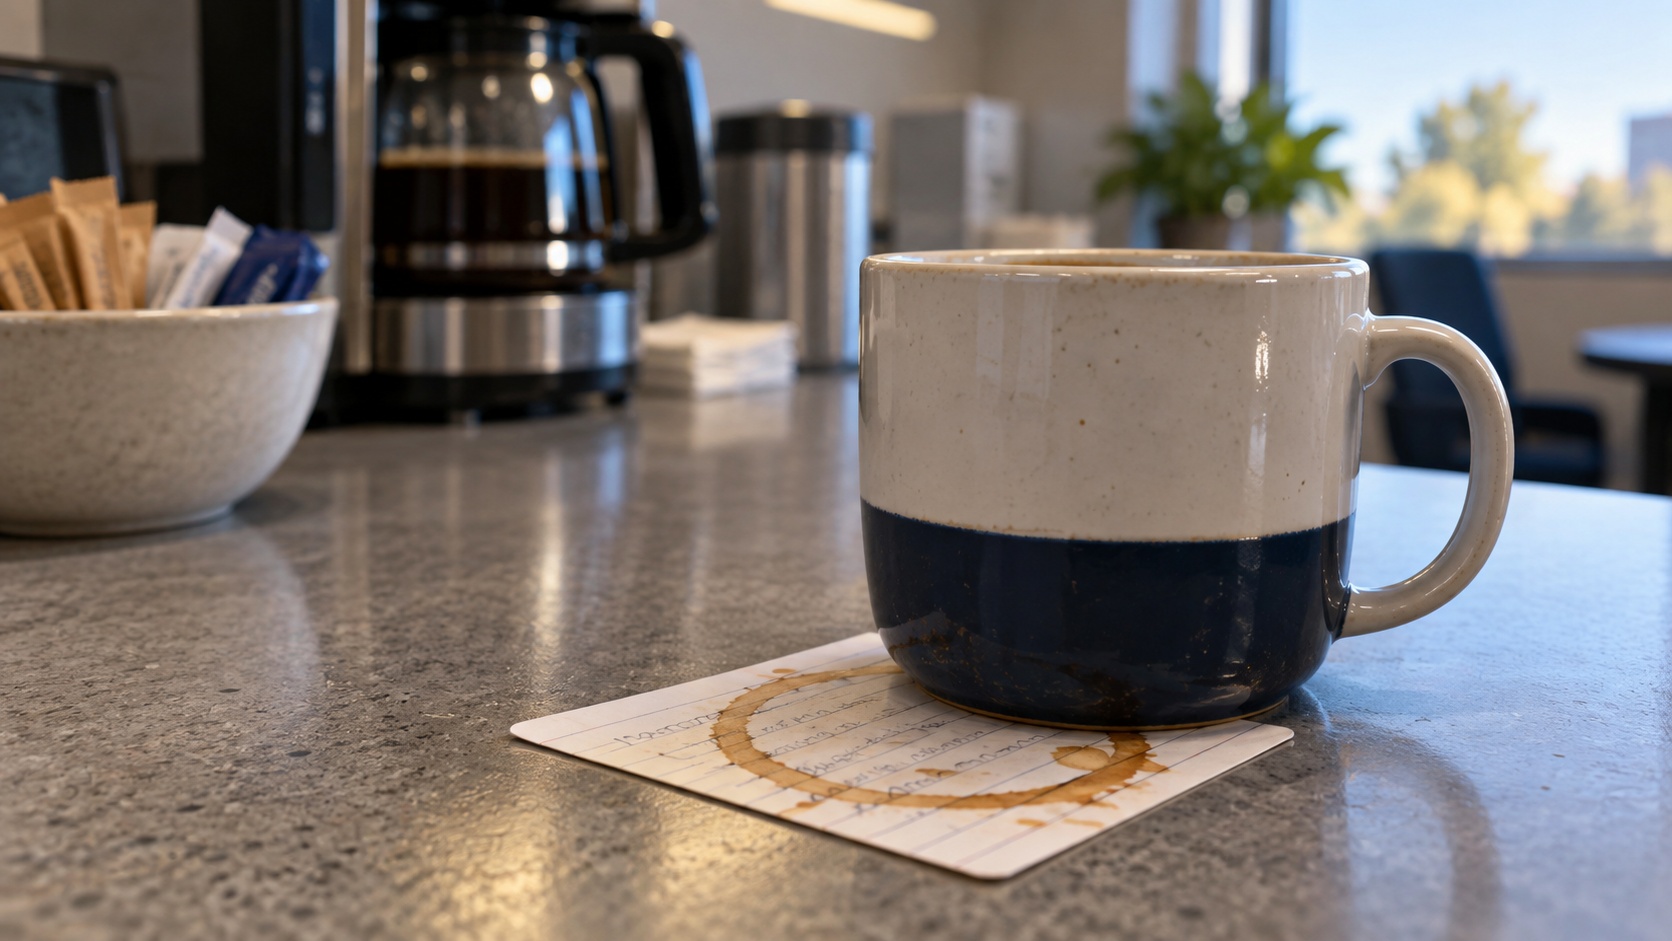
So she writes the number on an index card, along with what it is costing the company in credit line interest, and leaves it on the break room counter next to the coffee machine.
The VP of Sales picks it up, looks at it, and uses it as a coaster.
The bank call, when it came, communicated the message more clearly than any of these methods.
How do you calculate days sales outstanding?
Days sales outstanding equals accounts receivable divided by annual revenue, multiplied by 365.
A business with $9.5 million in revenue and $1.3 million in receivables is carrying roughly 50 days of DSO. Run it quarterly and chart the trend. The benchmark that matters is not your industry average. It is your own number, quarter over quarter.
What does DSO drift actually cost?
Take a $20 million business operating at 30-day DSO. Revenue is invoiced and converts to cash inside a month. The promise and the fact stay close together.
Now the business grows. A few key clients request net-60. A couple of large wins arrive with net-45 built into the deal. Nobody pushes back, because the revenue feels like a victory. DSO drifts from 30 days to 75. Nobody notices immediately, because the income statement looks fine. Better, even. Revenue is up.
At $20 million in annual revenue, $54,795 crosses the threshold every single day. Forty-five extra days of that revenue sitting with customers instead of in your account is $2.47 million in cash that belongs to the business, is owed to the business, and is not available to the business.
That is not a rounding error. That is a hiring plan. That is a debt paydown. That is three months of payroll headroom.
Why does DSO creep without anyone noticing?
Because it is nobody's number.
Sales owns the close. Operations owns delivery. Finance owns the report. Days sales outstanding sits between all three, which means it belongs to no one, which means it drifts.
In the book, a $9.5 million professional services firm watched DSO move from 45 days to 72 over two years as it won larger enterprise accounts on net-60 terms and let collections become informally deprioritized. Daily revenue was $26,027. The 27-day increase trapped $702,740 in receivables that had previously collected in half the time.
The firm's line of credit, essentially unused for years, was 60% drawn. Not to fund growth. To fund the gap between when they delivered work and when clients paid for it. The line was financing their customers' cash flow at 7.25% interest.
Why is DSO the most controllable number in your cash cycle?
Because unlike the other two components of the cash conversion cycle, it depends almost entirely on you.
Days inventory outstanding depends on suppliers, demand forecasting, and production logistics. Days payable outstanding depends on supplier relationships and your market position. Days sales outstanding depends on internal process: when you invoice, how you follow up, and what payment behavior you accept.
Most DSO improvement requires policy clarity and execution discipline. It does not require capital investment or external negotiation. That makes it the fastest money in most businesses.
How do I reduce DSO without damaging client relationships?
Four changes, in order of speed.
Invoice faster. Every day between delivery and invoice issuance is a day added to DSO before the clock even starts with the customer. For project-based businesses, month-end invoicing batches are a large and avoidable source of drift. Invoice on the day of delivery sign-off, not on the last business day of the month. One firm in the book cut nine days of DSO in a single quarter on that change alone, and another freed $750,000 with a similar fix.
Set expectations at the point of sale. Clients who learn your payment policy at the close pay faster than clients who encounter it for the first time on an invoice. Put it in the conversation: our standard terms are net-30, we process by ACH, here is how to set that up.
Formalize the follow-up. Most businesses have informal collections. A reminder at 30 days past due. A phone call at 60. Discomfort at 90. Define the outreach at specific intervals, assign it to a named person, and escalate to the senior relationship owner at a defined threshold. This does not make you more aggressive. It makes you consistent. Customers who know you will follow up reliably at 30 days pay closer to 30 days.
Flag non-standard terms before the deal closes. If a deal is going out at net-75, finance needs to know at signature so those accounts can be scheduled for earlier outreach. In the book, a VP of Sales closes $840,000 on net-75 to win the quarter and does not mention the terms in his pipeline report. He mentions the deal size. Twice.
None of this is adversarial. Clients who respect you pay on time. Clients who take 90 days without discussion are using your working capital as a free loan, and that conversation is easier to have at the start of a relationship than after the invoice is overdue.
What does a realistic improvement look like?
The firm above did four things: tighter invoice timing, standardized collections follow-up at 30, 45, and 55 days, a policy requiring new enterprise clients to set up ACH, and terms visibility at close.
Within two quarters, DSO went from 72 days back to 51. Eleven days of that improvement freed $286,000 in cash and cut the credit line draw in half.
No new customers. No capital raise. No new software. A process somebody finally owned.
What is the number your CFO is already trying to tell you?
Here is the part of the story that is not funny.
That CFO had the right number fourteen months before anyone acted on it. The information was not missing. The conditions for it to travel were.
In almost every company I have walked into, there is someone who knows. Someone quietly watching a number move in the wrong direction, who has the detail and the context and the three-year comparison, waiting for the right moment, the right question, the right room.
If your response to an early warning is frustration or dismissal, the information stops coming early. It arrives later and later, closer to the point where it is unavoidable rather than inconvenient. If the response is curiosity and action, it starts arriving sooner. Sooner is almost always enough time to do something.
Ask whoever runs your receivables what your DSO was twelve months ago and what it is today. They will have the answer immediately. That should tell you something.
Frequently asked questions
What is a good DSO?
It depends on your terms and industry, but a useful rule is that DSO should sit within 10 to 15 days of your stated payment terms. A company on net-30 running 68-day DSO does not have a terms problem. It has a process problem.
Does offering an early payment discount work?
It can. A common structure is 1% off for payment within 10 days on a net-30 invoice, written as 1/10 net 30. It works best with customers who have the cash to use it. Price the discount against what the delay is costing you on your credit line before you offer it.
Who should own DSO in my company?
One named person, reviewed weekly. No one owns a trend. Someone owns a metric. The most common working arrangement is the CFO or controller owning the number, with sales accountable for terms at close and operations accountable for invoice timing.
Call to action
Get the book. Days sales outstanding is one chapter of Profitable and Broke: What Your Cash Flow Reveals About Your Leadership. The rest of it covers the other two halves of the cash conversion cycle, the 13-week forecast, and the five warning signs that appear before growth turns into a cash crisis.
If you would rather have someone run the numbers with you, book a free 30-minute cash flow call with C-Suite Support and bring your receivables aging.
About the author
Paul Whitley is the Founder and CEO of C-Suite Support, a Texas-based fractional executive firm that provides fractional CFO, COO, and CMO services to owner-led businesses across Dallas-Fort Worth, Houston, Austin, and North Texas. Paul Whitley has spent more than thirty years as a CFO, COO, CMO, and general manager for companies ranging from $1.5 million to $5 billion in revenue, and has helped raise more than $336 million in public debt, private equity, bank debt, and asset-backed financing. He is the author of Profitable and Broke: What Your Cash Flow Reveals About Your Leadership and the host of CEO Talks with Paul Whitley on the C-Suite Network.
Related reading
The Tuesday Call: Why a Profitable Business Runs Out of Cash. Why a profitable business runs out of cash, and the three numbers that close the gap.
The 13-Week Cash Flow Forecast, Explained. How to build a rolling 13-week cash forecast, and why honest beats accurate.